Veteran & VA Homebuyer Programs in Florida
The benefit you earned, and the homes it works on
BreakThru Realty helps Florida homebuyers find the homeownership programs worth asking about, understand how each one shapes the home search, connect with participating lenders, and find homes that fit. For veterans and servicemembers that means the VA home loan benefit and Florida’s own programs, and a search built around the VA’s property rules, which decide more South Florida purchases than buyers expect.
See which programs are worth asking about · Homes within the limits
What the VA Asks of the Home
The VA does not lend money; it guarantees part of a loan made by a VA-approved lender, and eligibility starts with a Certificate of Eligibility, which a lender can usually request quickly. The home then has to satisfy the VA. Before the loan is approved, a VA appraiser checks the property against the VA’s minimum property requirements and issues a Notice of Value. A home with a failing roof, exposed wiring or no working systems can stop a VA purchase, which is why condition belongs in the search from the first showing.
- Detached single-family homes and townhomes
- Two- to four-unit residential income property, when the veteran lives in one unit
- Condominiums, which need VA approval of the project or a waiver
- Manufactured homes
- New construction, closing when the home is complete
A Condo Needs VA Approval of the Building
The VA lists condominiums as eligible only when the project has VA approval or a waiver. Approval belongs to the whole building, not to the unit, and many South Florida buyers start their search with condominiums, so it is the first question to settle here. We check the VA’s approved condominium search before an offer on any condo. The listings on this page leave condominiums out for the same reason and show single-family homes, townhomes, villas and small multifamily property instead.
Making a VA Offer Sellers Take Seriously
Some sellers still hesitate over VA offers. The VA’s own figures answer most of the doubt: in 2023, VA purchase loans took an average of 32 days to close against 45 for conventional loans, and 90% of initial VA purchase appraisals met or exceeded the contract price. The rest is how the offer is written: a clean contract with the VA escape clause, realistic dates, a strong pre-approval letter, and a plan for the appraisal. If an appraiser expects to come in low, the VA’s Tidewater process lets the point of contact named in the appraisal order send additional sales data before the value is final, and a reconsideration of value can be requested through the lender afterward.
The Appraisal Is Not an Inspection
A VA appraisal protects the loan; it does not look at the home the way a buyer needs it looked at. The VA does not require a home inspection but recommends one, and in South Florida the inspection is where you learn the roof’s age, the condition of the windows and shutters, the wind mitigation features that drive insurance cost, and any sign of water intrusion. We schedule it inside the inspection period and read the report with you before deciding whether to negotiate, ask for repairs or walk away.
Florida Programs Open to Veterans
Florida Hometown Heroes names servicemembers of every branch, including the reserves, the Coast Guard and the Florida National Guard, and veterans employed full time by a Florida-based employer, with down payment and closing cost assistance of up to 5% of the first mortgage amount, with a $10,000 minimum and a $35,000 maximum. Florida Housing also states that veterans do not have to be first-time homebuyers for its government loan program. Consult a mortgage lender who participates in Florida Housing’s programs to see how a VA loan and these Florida programs fit together for you.
Florida Property Tax Benefits for Veterans
Florida’s property tax benefits for veterans can change what owning a particular home costs, so they belong in the comparison between homes. You apply to the property appraiser in the county where the home is; the general deadline for exemptions is March 1. The Florida Department of Revenue notes that eligible veterans may apply before they receive the supporting documentation from the VA, with the exemption effective from the original application date once it arrives, and that a servicemember may rent out a homestead without abandoning the exemption.
- A $5,000 reduction in assessed value for an honorably discharged veteran who is a Florida resident and disabled to a degree of 10% or more because of misfortune or while serving during wartime. It is not limited to homestead property. (section 196.24, Florida Statutes)
- A total exemption from property taxes on the homestead of a veteran who is a Florida resident and was honorably discharged with a service-connected total and permanent disability, with a similar exemption for disabled veterans confined to wheelchairs. (section 196.081 and 196.091, Florida Statutes)
- A discount on the assessed value of the homestead for a veteran 65 or older who is partially or totally permanently disabled, equal to the percentage of the veteran’s permanent, service-connected disability as determined by the VA. (section 196.082, Florida Statutes)
- An exemption for servicemembers deployed outside the continental United States, Alaska and Hawaii in support of a designated operation, in proportion to the time deployed during the previous year. (section 196.173, Florida Statutes)
Who Florida Housing Lists for Hometown Heroes
Full-time, current employment with a Florida-based employer. Florida Housing’s examples in each group include, but are not limited to, the titles below.
Servicemembers and veterans
Employed by for veterans, a Florida-based employer, full time; servicemembers qualify through their service.
- Active duty and reserve members of every branch of the U.S. Armed Forces, including the Florida National Guard
- Veterans employed full time by a Florida-based employer, discharged under other than dishonorable conditions
Program Limits by County
| County | Hometown Heroes income limit | FHA loan limit | HFA Advantage and VA loan limit | SHIP purchase price limit |
|---|---|---|---|---|
| Broward County | $190,200 | $667,000 | $832,750 | $679,324 |
| Miami-Dade County | $204,300 | $667,000 | $832,750 | $679,324 |
| Palm Beach County | $192,750 | $667,000 | $832,750 | $679,324 |
| Martin County | $153,600 | $603,750 | $832,750 | $619,629 |
| St. Lucie County | $153,600 | $603,750 | $832,750 | $619,629 |
| Indian River County | $153,450 | $541,287 | $832,750 | $544,233 |
Houses, Townhomes and Villas Within the Program Limits
Broward County: at or below $667,000
Houses, townhomes and villas listed at or below the 2026 FHA loan limit Florida Housing publishes for Broward County, in property types its programs allow. A starting point, not a qualification: your pre-approval sets your own number.
 $199,999
204 SW 120TH Avenue 204, Pembroke Pines FL 33025
2 bd · 3 ba · 1,338 sq ft · Townhouse$639,999
5400 NW 57th Court, Tamarac FL 33319
4 bd · 3 ba · 1,862 sq ft · Single Family Residence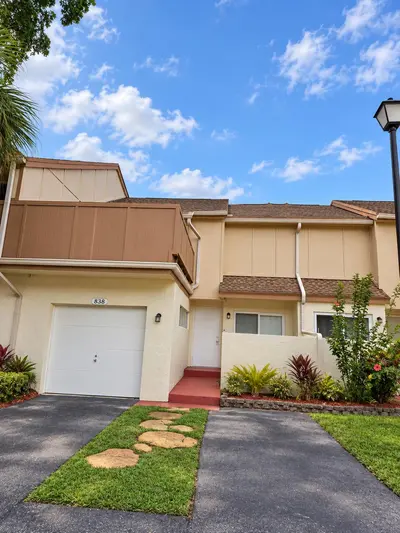 $269,000
838 NW 82ND Avenue 2, Plantation FL 33324
3 bd · 3 ba · 1,770 sq ft · Townhouse$590,000
1853 SW 176th Way, Miramar FL 33029
3 bd · 3 ba · 1,862 sq ft · Single Family Residence
See every Broward County home at or below this line
Miami-Dade County: at or below $667,000
Houses, townhomes and villas listed at or below the 2026 FHA loan limit Florida Housing publishes for Miami-Dade County, in property types its programs allow. A starting point, not a qualification: your pre-approval sets your own number.
$515,000
14905 SW 304th Terrace, Homestead FL 33033
4 bd · 3 ba · 1,721 sq ft · Single Family Residence$340,000
1084 SE 13th Avenue, Homestead FL 33035
3 bd · 3 ba · 1,488 sq ft · Townhouse$480,000
10551 SW 141st Drive, Miami FL 33176
3 bd · 1 ba · 1,156 sq ft · Single Family Residence$650,000
1085 NE 203rd Lane, Miami FL 33179
3 bd · 2 ba · 1,674 sq ft · Single Family Residence
See every Miami-Dade County home at or below this line
Palm Beach County: at or below $667,000
Houses, townhomes and villas listed at or below the 2026 FHA loan limit Florida Housing publishes for Palm Beach County, in property types its programs allow. A starting point, not a qualification: your pre-approval sets your own number.
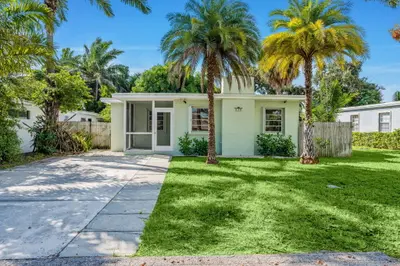 $489,000
128 E Central Boulevard, Lantana FL 33462
2 bd · 2 ba · 1,108 sq ft · Single Family Residence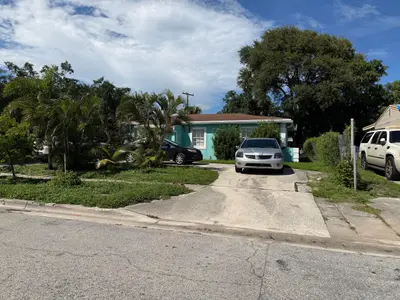 $399,000
386 W 15TH Street, Riviera Beach FL 33404
4 bd · 2 ba · 1,548 sq ft · Single Family Residence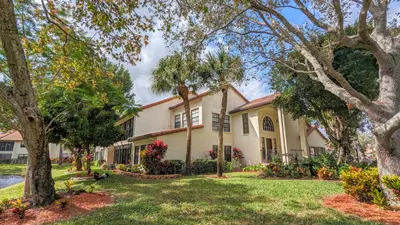 $279,000
3002 Lucerne Park Drive 5121, Greenacres FL 33467
2 bd · 2 ba · 1,558 sq ft · Townhouse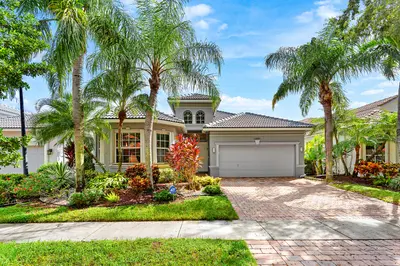 $619,900
10086 Mizner Falls Way, Boynton Beach FL 33437
3 bd · 3 ba · 2,343 sq ft · Single Family Residence
See every Palm Beach County home at or below this line
Martin County: at or below $603,750
Houses, townhomes and villas listed at or below the 2026 FHA loan limit Florida Housing publishes for Martin County, in property types its programs allow. A starting point, not a qualification: your pre-approval sets your own number.
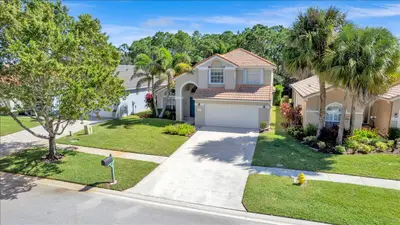 $565,000
7119 SE Twin Oaks Circle, Stuart FL 34997
3 bd · 3 ba · 2,312 sq ft · Single Family Residence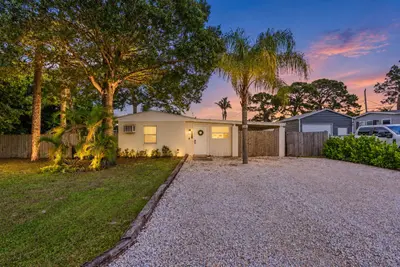 $340,000
5317 SE ISABELITA Avenue, Stuart FL 34997
2 bd · 1 ba · 987 sq ft · Single Family Residence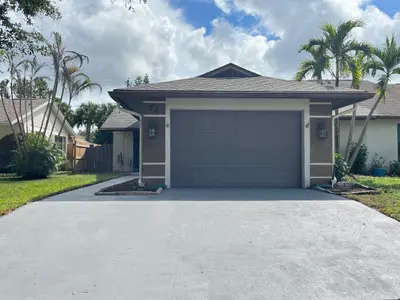 $375,000
72 SE Taho Terrace, Stuart FL 34997
3 bd · 2 ba · 1,364 sq ft · Villa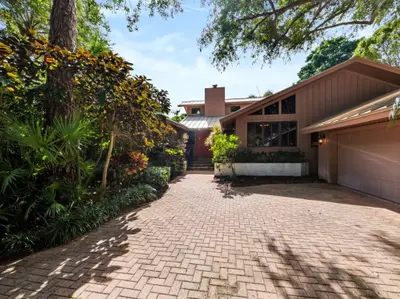 $585,000
5011 SE Burning Tree Circle, Stuart FL 34997
3 bd · 3 ba · 2,800 sq ft · Single Family Residence
See every Martin County home at or below this line
St. Lucie County: at or below $603,750
Houses, townhomes and villas listed at or below the 2026 FHA loan limit Florida Housing publishes for St. Lucie County, in property types its programs allow. A starting point, not a qualification: your pre-approval sets your own number.
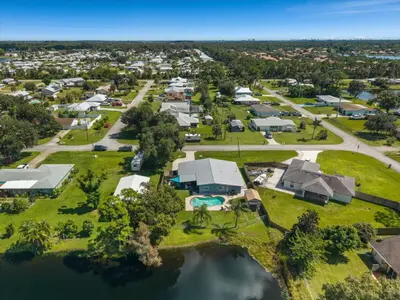 $350,000
6005 Lantana Drive, Fort Pierce FL 34951
3 bd · 3 ba · 1,702 sq ft · Single Family Residence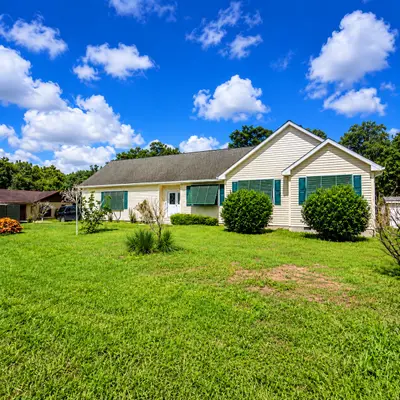 $350,000
3162 DAME Road, Fort Pierce FL 34981
3 bd · 2 ba · 1,886 sq ft · Single Family Residence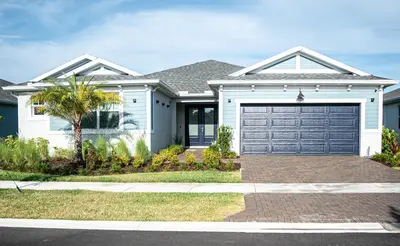 $550,000
10317 SW Phineas Lane, Port St. Lucie FL 34987
4 bd · 3 ba · 2,747 sq ft · Single Family Residence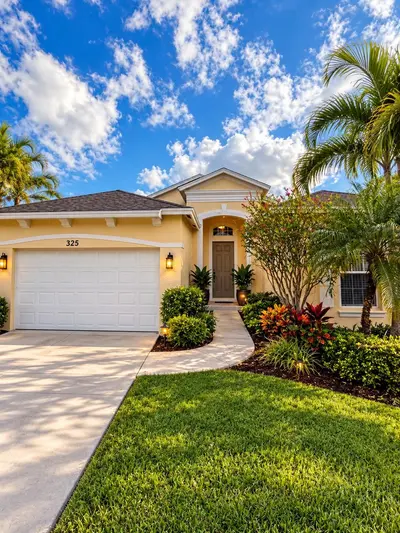 $320,000
325 SW North Shore Boulevard, Port St. Lucie FL 34986
2 bd · 2 ba · 1,573 sq ft · Single Family Residence
See every St. Lucie County home at or below this line
Indian River County: at or below $541,287
Houses, townhomes and villas listed at or below the 2026 FHA loan limit Florida Housing publishes for Indian River County, in property types its programs allow. A starting point, not a qualification: your pre-approval sets your own number.
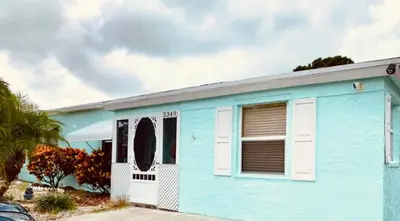 $333,888
2349 Old Dixie Highway, Vero Beach FL 32962
4 bd · 4 ba · 1,900 sq ft · Single Family Residence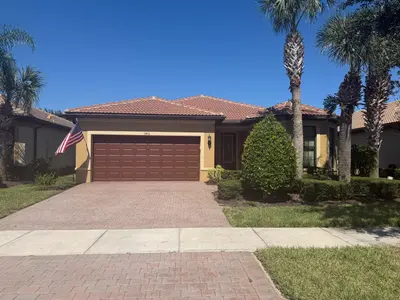 $435,000
5401 ANTIGUA Circle, Vero Beach FL 32967
2 bd · 2 ba · 1,683 sq ft · Single Family Residence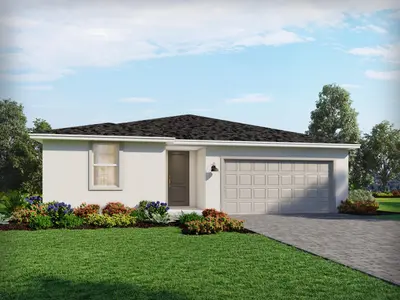 $399,990
5505 HAMPTON PARK Circle, Vero Beach FL 32966
4 bd · 2 ba · 1,840 sq ft · Single Family Residence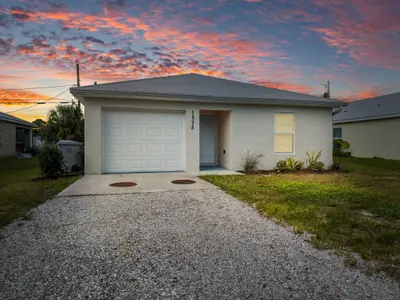 $275,000
1575 21st Avenue, Vero Beach FL 32962
3 bd · 2 ba · 1,140 sq ft · Single Family Residence
See Which Programs Are Worth Asking About
Tell us what you do, the county you are looking in, your timing, whether you have owned a home in the last three years and your price range. We send back the programs worth raising with a participating lender and homes that fit them. Questions about credit, income and debts belong with your lender, so they are not on the form.
Prefer to talk? (786) 914-1017 · sales@breakthrurealty.com
Frequently Asked Questions
- Can I use a VA loan to buy a condo in Florida?
- Yes, if the condominium project has VA approval or a waiver. Approval belongs to the building, not the unit, and the VA publishes a search of approved condominiums. Check it before you make an offer, because a condo in a building without approval cannot be bought with a VA-guaranteed loan as it stands.
- Do veterans have to be first-time buyers for Florida Housing programs?
- Florida Housing states that veterans do not have to be first-time homebuyers for its government loan program. VA home loans themselves have no first-time requirement, and the benefit can be used more than once. Consult a mortgage lender about how your entitlement and Florida’s programs work together.
- Is there a VA loan limit in South Florida?
- The VA states that since 2020, a buyer with full entitlement has no VA loan amount limit, provided the loan does not exceed the appraised value and the buyer meets the lender’s requirements. Entitlement already in use on another loan changes that picture, so consult a mortgage lender who participates in Florida Housing’s programs or any VA-approved lender to confirm yours.
- What property tax exemptions do disabled veterans get in Florida?
- Florida offers a $5,000 reduction in assessed value for honorably discharged veterans with a disability of 10% or more, a total exemption on the homestead of a veteran with a service-connected total and permanent disability, and a discount for veterans 65 or older equal to their VA disability percentage. Apply to the county property appraiser.
- Do South Florida sellers accept VA offers?
- They do, and the VA’s own figures help make the case: in 2023, VA purchase loans closed in 32 days on average against 45 for conventional loans, and 90% of initial VA purchase appraisals met or exceeded the contract price. A clean offer, realistic dates and a strong pre-approval do the rest.
- Is a home inspection required with a VA loan?
- No. The VA does not require a home inspection, but it strongly recommends one, because the VA appraisal is not an inspection. In South Florida the inspection is where you learn about the roof, the windows and shutters, wind mitigation and any water intrusion, all of which affect insurance and repair costs.
Sources
- VA Loan Guaranty Service: Quick Reference for Real Estate Professionals
- U.S. Department of Veterans Affairs: VA home loan eligibility
- VA: condo report and approved condominium search
- Florida Housing Finance Corporation: Hometown Heroes Program
- Florida Housing Finance Corporation: Homebuyer Loan Programs
- Florida Department of Revenue: Property Tax Benefits for Active Duty Military and Veterans (PT-109)
- Florida Statutes, section 196.011: annual application for exemption, due March 1
Program figures checked against their published sources on September 23, 2026. Programs, limits and funding change; consult a mortgage lender who participates in Florida Housing’s programs for the current terms.
More Homebuyer Programs
Related on BreakThru Realty
- How BreakThru Realty works with buyers
- Search every South Florida home for sale
- Broward County real estate
- Miami-Dade County real estate
- Palm Beach County real estate
- Martin County real estate
- St. Lucie County real estate
- Indian River County real estate
- BreakThru Realty Research: housing market reports
- New construction homes