Bank-Owned Homes for Sale in South Florida
Every bank-owned home, condo and townhome currently listed for sale across South Florida, straight from the MLS and updated throughout the day.
A bank-owned home, or REO, is one the lender already took back at the foreclosure auction and now owns outright. It is the most common distressed listing in South Florida and the simplest to buy: there is no borrower left in the deal, no second lender to approve a discount and no judge to wait for, so the bank can accept your offer and close on an ordinary timeline. The trade-off is condition. REO homes are sold strictly as-is, usually with no seller disclosure because the bank never lived there, often with the appliances, air-conditioning or pool equipment stripped out, and sometimes with the utilities off so an inspector cannot test anything. Budget for a full inspection, a roof and air-conditioning quote and the possibility of a cash-only purchase if the home will not appraise for financing.
46 listings, newest first.
$299,900
7736 Colee Cove Road, St. Augustine FL 32092
3 bd · 2 ba · 1,400 sq ft · Single Family Residence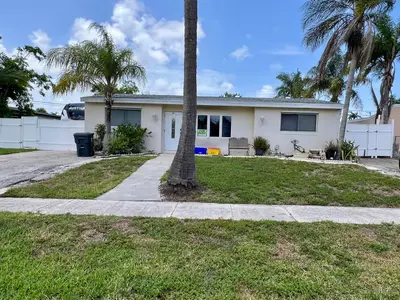 $419,999
591 Tallulah Road, Lake Worth FL 33462
2 bd · 2 ba · 993 sq ft · Single Family Residence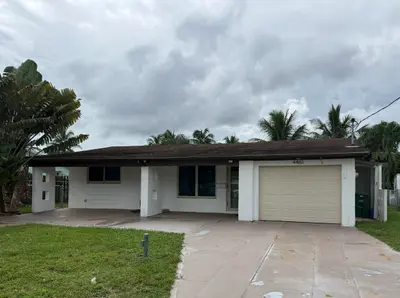 $619,900
4461 SW 34TH Drive, Dania Beach FL 33312
4 bd · 2 ba · 1,543 sq ft · Single Family Residence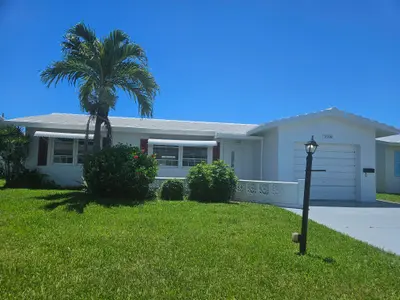 $190,000
1598 SW 13TH Terrace, Boynton Beach FL 33426
2 bd · 2 ba · 1,428 sq ft · Single Family Residence$565,000
4261 SW 164th Court, Miami FL 33185
3 bd · 3 ba · 1,488 sq ft · Townhouse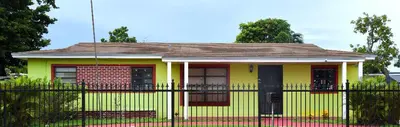 $650,000
, Miami Gardens FL 33055
4 bd · 2 ba · 1,748 sq ft · Single Family Residence $149,900
6725 NE 8th Lane, Okeechobee FL 34974
3 bd · 2 ba · 1,512 sq ft · Manufactured Home $105,000
2751 E GOLF Boulevard 2028, Pompano Beach FL 33064
2 bd · 1 ba · 750 sq ft · Condominium $419,000
3451 NW 6TH Street, Lauderhill FL 33311
4 bd · 2 ba · 1,386 sq ft · Single Family Residence$325,000
5712 NW 68th Terrace, Tamarac FL 33321
2 bd · 2 ba · 1,587 sq ft · Single Family Residence $169,900
503 W 16th Street, Jacksonville FL 32206
4 bd · 2 ba · 1,216 sq ft · Single Family Residence$1,799,000
7541 NW 100th Avenue, Doral FL 33178
6 bd · 7 ba · 4,306 sq ft · Single Family Residence $259,500
2400 S OCEAN Drive 1034, Fort Pierce FL 34949
1 bd · 0 ba · 689 sq ft · Condominium $349,900
374 SW Homeland Road, Port St. Lucie FL 34953
3 bd · 2 ba · 1,544 sq ft · Single Family Residence $799,900
8911 NW 178th Lane, Hialeah FL 33018
4 bd · 3 ba · 2,124 sq ft · Single Family Residence$850,000
4539 NW 83rd Parkway, Doral FL 33166
3 bd · 4 ba · 1,866 sq ft · Townhouse$5,490,000
799 Crandon Boulevard 202, Key Biscayne FL 33149
4 bd · 6 ba · 3,581 sq ft · Condominium$425,000
105 NW 58th Street, Miami FL 33127
4 bd · 2 ba · 1,897 sq ft · Single Family Residence$1,095,000
1861 W Eagle Trace Boulevard, Coral Springs FL 33071
5 bd · 5 ba · 3,023 sq ft · Single Family Residence$1,300,000
45 SW 9th Street 4303, Miami FL 33130
3 bd · 3 ba · 1,447 sq ft · Condominium$410,000
13027 Lily Pond Court, Orlando FL 32824
3 bd · 3 ba · 1,996 sq ft · Single Family Residence $169,900
6091 Village Circle 6091, Orlando FL 32822
2 bd · 3 ba · 1,128 sq ft · Condominium $299,900
5163 MARION Place, West Palm Beach FL 33407
0 bd · 3 ba · 1,778 sq ft · Single Family Residence$1,029,950
3405 Robbins Road, Pompano Beach FL 33062
4 bd · 2 ba · 1,792 sq ft · Single Family Residence $270,000
499 E Iron Forge Court, Royal Palm Beach FL 33411
3 bd · 2 ba · 1,120 sq ft · Villa $583,000
2860 S Ocean Boulevard 209, Palm Beach FL 33480
1 bd · 2 ba · 1,012 sq ft · Condominium $540,000
9538 NW 8th Circle, Plantation FL 33324
3 bd · 2 ba · 1,566 sq ft · Single Family Residence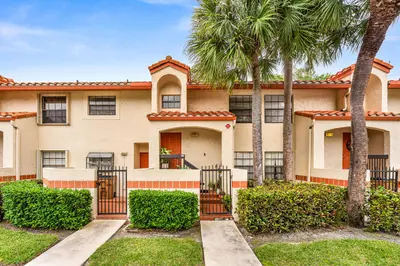 $275,000
906 CONGRESSIONAL Way 906, Deerfield Beach FL 33442
2 bd · 2 ba · 1,150 sq ft · Condominium$1,195,000
13248 SW 188th Terrace, Miami FL 33177
5 bd · 5 ba · 3,456 sq ft · Single Family Residence$480,000
1091 Salih Street, Opa-Locka FL 33054
4 bd · 2 ba · 1,428 sq ft · Single Family Residence$849,000
2135 NW 1st Terrace, Miami FL 33125
0 ba · 2,133 sq ft · Duplex$605,000
16101 Emerald Estates Drive 448, Weston FL 33331
2 bd · 3 ba · 1,529 sq ft · Condominium$283,900
631 Jefferson Avenue 304, Miami Beach FL 33139
1 bd · 1 ba · 660 sq ft · Condominium$825,000
15221 SW 158th Street, Miami FL 33187
4 bd · 2 ba · 2,067 sq ft · Single Family Residence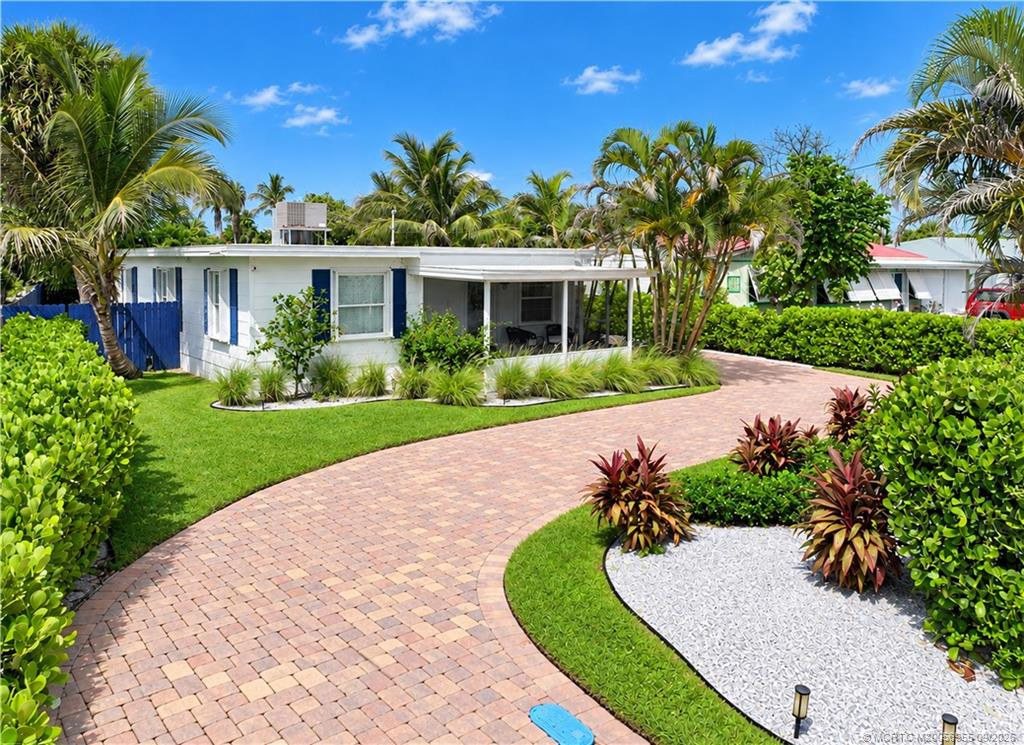 $619,888
307 Granada Street, Fort Pierce FL 34949
4 bd · 2 ba · 1,304 sq ft · Single Family Residence$269,000
10729 La Placida Drive 3-4, Coral Springs FL 33065
2 bd · 2 ba · 1,150 sq ft · Condominium $323,000
2562 SE Petit Lane, Port St. Lucie FL 34952
3 bd · 2 ba · 1,712 sq ft · Single Family Residence $199,000
7101 GOLF COLONY Court 201, Lake Worth FL 33467
2 bd · 2 ba · 790 sq ft · Condominium$449,900
3225 NE 13th Street 201, Pompano Beach FL 33062
3 bd · 3 ba · 1,650 sq ft · Townhouse$1,200,000
4224 SW 60th Place, South Miami FL 33155
0 ba · 2,458 sq ft · Duplex $165,000
1850 NW 18TH Street 101, Delray Beach FL 33445
2 bd · 2 ba · 1,335 sq ft · Condominium $259,000
4651 SE CHATHAM Avenue, Stuart FL 34997
2 bd · 1 ba · 954 sq ft · Single Family Residence$325,000
7933 E West Drive 1025, North Bay Village FL 33141
2 bd · 2 ba · 1,000 sq ft · Condominium$655,000
10321 Fairway Heights Boulevard, Miami FL 33157
3 bd · 1 ba · 1,918 sq ft · Single Family Residence$199,000
2890 N Oakland Forest Drive 202, Oakland Park FL 33309
2 bd · 2 ba · 981 sq ft · Condominium$660,000
11389 SW 185th Terrace, Miami FL 33157
4 bd · 2 ba · 1,813 sq ft · Single Family Residence
Bank-Owned (REO) Homes: Frequently Asked Questions
- What does bank-owned or REO mean?
- It means the lender foreclosed, nobody bought the home at the courthouse auction, and the bank took title. "REO" stands for real estate owned, the accounting term for property a bank owns rather than lends against. The bank is now an ordinary seller: it lists the home with an agent, reviews offers and closes at a title company.
- Are bank-owned homes cheaper?
- Often, but not always, and never by the margins the late-night seminars promise. Banks price REO homes from a broker price opinion at or slightly below market for the condition the home is in, and in a tight South Florida market a clean REO can draw several offers and sell above asking. The discount that is real is in the condition, which is also the risk.
- Can I get a mortgage on a bank-owned home?
- Yes, if the home is in lendable condition. Conventional and FHA loans both work on an REO purchase, but FHA has minimum property standards, and a home with a failed roof, missing water heater or no working kitchen will not pass. Those homes sell to cash buyers or to borrowers using a renovation loan such as the FHA 203(k).
- How is an REO offer different from a normal offer?
- You sign the bank's own addendum, which usually replaces most of the standard Florida contract: as-is with the right to inspect, no seller repairs, no disclosures, per-diem penalties if you miss the closing date, and the bank choosing the title company. We read that addendum with you line by line before you sign, because it is where the leverage in an REO deal actually sits.
- How fast do I have to move?
- Fast. Well-priced REO listings in Broward, Miami-Dade and Palm Beach counties frequently go under contract within days, and many banks review offers only on set dates. Being pre-approved or having proof of funds ready is the difference between making the list and watching the home sell.
Facing foreclosure on your own home?
Selling before the judgment usually protects your credit better than losing the home at the clerk's sale, and where there is equity it puts the surplus in your pocket instead of the court registry. Find out what your home is worth today, request a cash offer, or read what your options are once you have been served.