Foreclosed Homes for Sale in South Florida
Homes listed for sale while a foreclosure case is open against them, straight from the MLS and updated throughout the day.
These are homes with a foreclosure case already filed and still working through the Florida courts, listed for sale by the owner before the judge sets a sale date. Florida forecloses judicially, so the process runs through a lawsuit that commonly takes a year or more, and until the clerk sells the home at auction the owner can still sell it and pay off the lender. That is what you are looking at here. A foreclosure listing can be a strong buy, because the seller has a deadline the market does not, but the deal only closes if the sale proceeds cover the mortgage, the arrears and the lender's legal fees, or the lender agrees to take less. Expect a title search that turns up more than usual, second mortgages, homeowner association liens, code enforcement fines and an open court case with a calendar of its own. This is a smaller list than the bank-owned one and it changes constantly, so check back or ask us to set an alert.
12 listings, newest first.
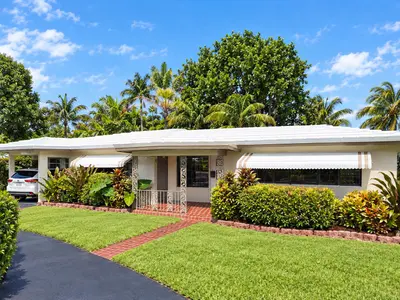 $625,000
601 NW 29th Street, Wilton Manors FL 33311
3 bd · 2 ba · 1,621 sq ft · Single Family Residence $624,900
1799 NW 124TH Way, Pembroke Pines FL 33028
4 bd · 3.5 ba · 3,033 sq ft · Townhouse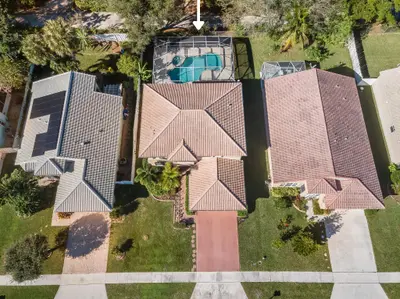 $619,000
6570 Spring Meadow Drive, Greenacres FL 33413
5 bd · 3 ba · 2,372 sq ft · Single Family Residence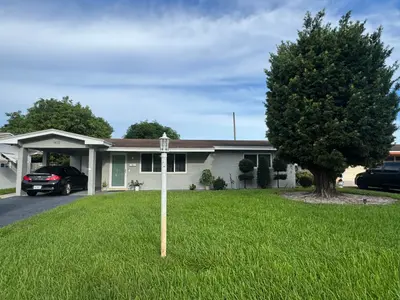 $440,000
1431 NW 79TH Way, Pembroke Pines FL 33024
3 bd · 2 ba · 1,537 sq ft · Single Family Residence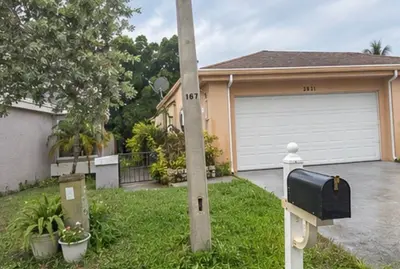 $499,000
2021 NW 35TH Terrace, Coconut Creek FL 33066
3 bd · 2 ba · 1,558 sq ft · Single Family Residence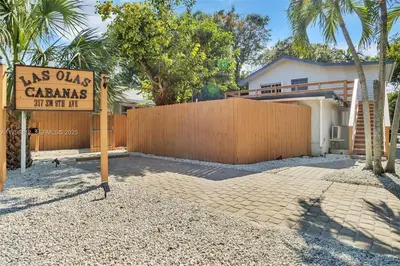 $750,000
317 SW 9TH Avenue 1-3, Fort Lauderdale FL 33312
0 ba · 1,820 sq ft · Triplex $465,000
2705 NW 73RD Avenue, Sunrise FL 33313
3 bd · 2 ba · 1,040 sq ft · Single Family Residence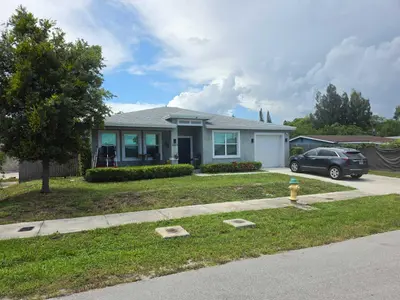 $494,900
2623 NW 18TH Terrace, Oakland Park FL 33311
3 bd · 2 ba · 1,666 sq ft · Single Family Residence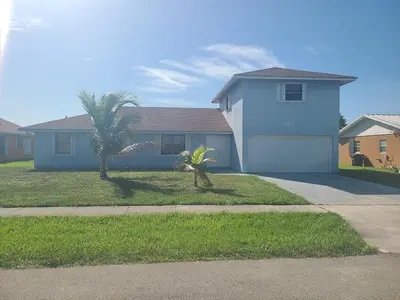 $499,000
1533 6TH Street, West Palm Beach FL 33401
5 bd · 2 ba · 2,010 sq ft · Single Family Residence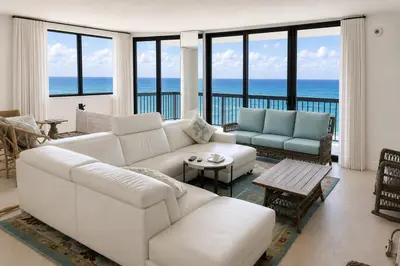 $585,000
5380 N Ocean Drive 4e, Singer Island FL 33404
2 bd · 2 ba · 1,586 sq ft · Condominium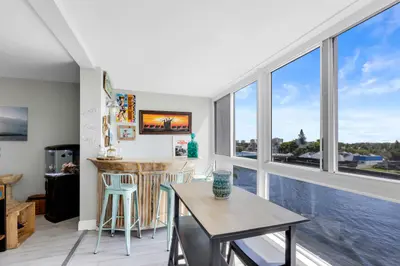 $465,000
3100 NE 49th Street 503, Fort Lauderdale FL 33308
2 bd · 2 ba · 1,400 sq ft · Condominium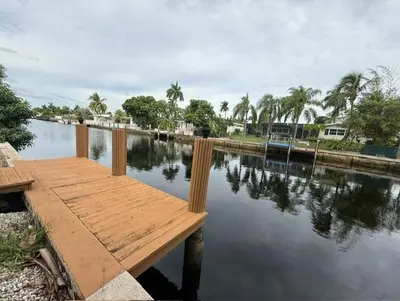 $895,000
1485 NE 57th Court, Fort Lauderdale FL 33334
4 bd · 3 ba · 2,094 sq ft · Single Family Residence
Foreclosure Listings: Frequently Asked Questions
- What is the difference between a foreclosure listing and a bank-owned home?
- Timing and who owns the home. A foreclosure listing is still owned by the borrower with a court case pending. A bank-owned home is one the lender already took back after the auction. The first is a negotiation with a homeowner racing a deadline; the second is a transaction with a bank.
- Can the sale fall through because of the court case?
- Yes. If the judge sets the foreclosure sale before you close, the home goes to the courthouse auction and your contract dies with it. A sale in this situation needs the closing agent and the seller's foreclosure attorney working together, and where necessary a motion to cancel or postpone the sale date. We manage that timeline rather than hoping it works out.
- How long does a Florida foreclosure take?
- A contested Broward or Miami-Dade foreclosure commonly runs twelve to twenty-four months from the filing of the lis pendens to the clerk's sale, and longer where the borrower raises defences or files for bankruptcy. An uncontested case can be finished in six to eight months.
- Do I have to pay the seller's back taxes and liens?
- Not out of your own pocket at closing, but they do have to be paid from the proceeds before clear title passes, which is exactly why some of these deals do not close. Property taxes, association dues, code fines and any second mortgage are searched before we write the offer so nobody finds them a week before closing.
- Is buying at the courthouse auction the same thing?
- No, and it is a different sport. A clerk's auction bid is cash, due within hours, with no inspection, no title insurance and no guarantee the home is empty. Everything on this page is an ordinary MLS listing you can tour, inspect, finance and insure.
Facing foreclosure on your own home?
Selling before the judgment usually protects your credit better than losing the home at the clerk's sale, and where there is equity it puts the surplus in your pocket instead of the court registry. Find out what your home is worth today, request a cash offer, or read what your options are once you have been served.